Reporting online property listings to Turkey’s tax authority: What changed on 5 September 2026?
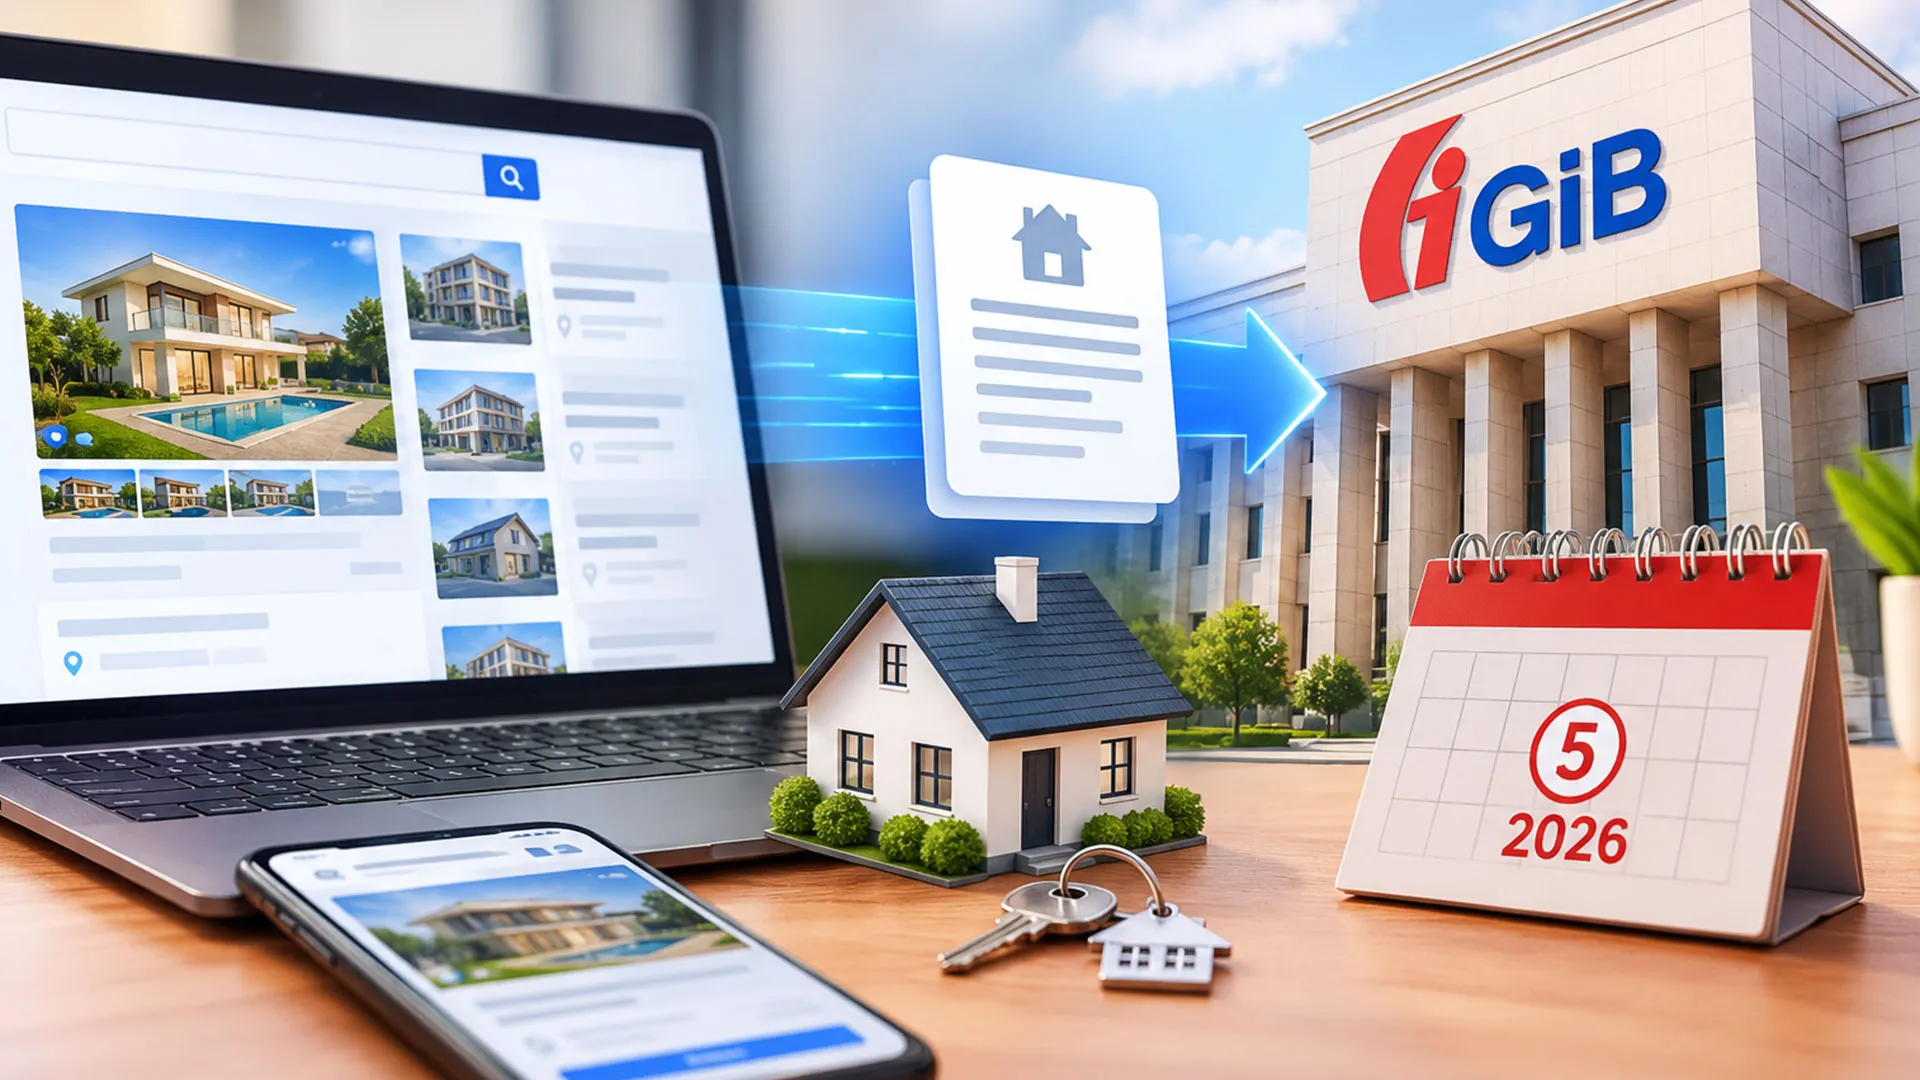
Published in Türkiye’s Official Gazette on 5 September 2026, Communiqué No. 595 amends Communiqué No. 538, which was issued in 2022. The rules are not limited to homes: they concern digital listings for the sale or rental of movable and immovable property, as well as goods and services.
Who must report?
The amendment updates the reporting rules for intermediary service providers that facilitate the publication of listings. It also sets out a separate monthly reporting requirement for hosting providers and social network providers that enable listings to be published. It does not mean that every homeowner posting an advertisement must personally file a monthly listing report with the Revenue Administration. Whether an operator is covered depends on the service it actually provides and the definitions in the Communiqué.
What information is covered?
For hosting and social network providers, the specified information includes the internet address where the service is provided; the name or business name of the person receiving the service; identifying tax information such as a Turkish identity number, foreign identity number or tax identification number; and details of the relevant sale or rental listing. Covered providers report electronically to the Turkish Revenue Administration (GİB) for monthly periods. The information required from intermediary service providers is addressed separately in the Communiqué.
Does posting a listing trigger a new tax?
Communiqué No. 595 does not impose a new tax merely because a property is advertised. The tax treatment of an actual sale or rental income must be assessed under the tax rules applicable to that transaction. Reporting can make it easier to compare listings with completed transactions, but an asking price is not, by itself, proof of the final sale price or the taxable amount.
Property owners and agents should keep listing details accurate and up to date. Whether a particular real estate website has its own reporting duty requires a review of how the website operates and which services it provides to others.
Official sources (Turkish): Official Gazette, Communiqué No. 595, 5 September 2026 · Revenue Administration announcement